所屬科目:研究所、轉學考(插大)◆成本學與管理會計學
(1) A company is looking to purchase and replace a fixed asset for $2,100,000. It will sell the asset that will be replaced for $410,000 but will incur a $10,000 gain upon that sale. It must also commit $300,000 of working-capital to the investment. The firm's tax rate is 20%. Required: What is the amount of the relevant initial investment?
(2) The NTPU Company orders most of its items in lot sizes of 10 units. Average annual demand per side of beef is 720 units per year. Ordering costs are $25 per order with an average purchasing price of $100. Annual inventory carrying costs are estimated to be 40% of the unit cost. Required: Determine the annual cost savings if NTPU Company changes its order size from 10 units to the economic order quantity.
(3) NTPU Corporation makes miniature statues of the Empire State Building from cast iron. Sales total 50,000 units a year. The statues are finished either rough or polished, with an average demand of 60% rough and 40% polished. Iron ingots, the direct material, costs $5 per pound. Processing costs are $300 to convert 30 pounds into 60 statues. Rough statues are sold for $17 each, and polished statues can be sold for $19 or engraved for an additional cost of $5. Polished statues can then be sold for $40. Required: Determine whether NTPU Company should sell the engraved statutes. Why?
(4) NTPU Corp is committed to its quality program. It works with all areas of the company to establish sound quality programs within reasonable budget guidelines. For 2026, it has budgeted $1,000,000 for prevention costs and $900,000 for appraisal costs. Internal failure has a budget of $100 per failed item, while external failure has a total budget of $600,000. Product Testing has proposed to management a change in the 2026 budget for a new method of testing products. If management decides to implement the new method, $1.5 per unit of appraisal costs will be saved, up to a level of 150,000 tests. No additional savings are expected past the 150,000 level. The new method involves $95,000 in training costs and $65,000 in yearly testing supplies. Traditionally, 5% of all completed items have to be reworked. External failure costs average $120 per failed unit. The company's average external failures are 1% of units sold. The company carries no ending inventories. Required: How much do internal failure costs change, assuming 500,000 units are tested under the new method and it reduces the amount of unacceptable units in the manufacturing process by 40%?
(5) LUKE is considering purchasing a new computer network for $82,000. It will require additional working capital of $13,000. Its anticipated eight-year life will generate additional client revenue of $33,000 annually with operating costs, excluding depreciation, of $15,000. At the end of eight years, it will have a salvage value of $9,500 and return $5,000 in working capital. Taxes are not considered. The company has a required rate of return of 14%. Required: What is the net present value of the proposed investment? What is the internal rate of return?
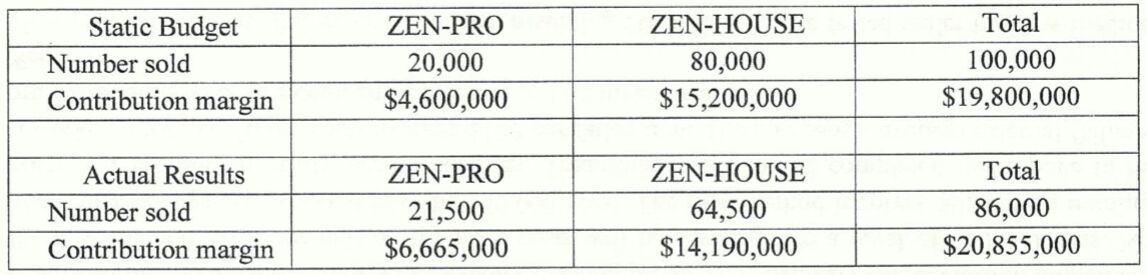
(6) NTPU Corporation manufactures two types of smartphone: ZEN-PRO, designed for commercial customers, and ZEN-HOUSE, designed for residential customers. Budgeted and actual operating data for the year 2025 are presented below: Required: Compute the sales-mix variance and the sales-quantity variance, by type of smartphone and in total, using the contribution margin (Use “F” to represent a favorable variance and “U” to represent an unfavorable variance).
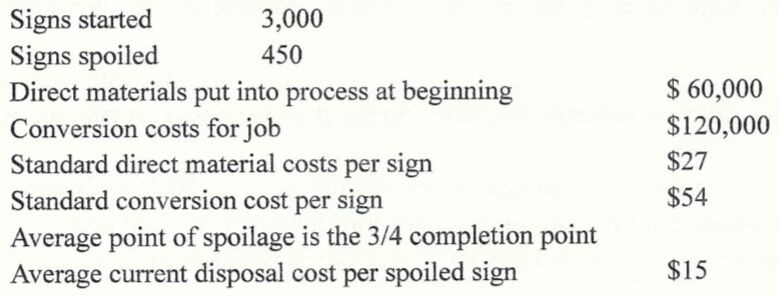
(1) NTPU Inc. manufactures only specific orders. It uses a standard cost system. During one large order for the airport authority, an unusual number of signs were spoiled. The normal spoilage rate is 10% of units started. The point of first inspection is half way through the process, the second is three-fourths through the process, and the final inspection is at the end of the process. Other information about the job is as follows: Required: Make necessary journal entries to record all spoilage.
(2) TSMC has budgeted construction overhead for August of $435,000 for fixed costs. Actual costs for the month totaled for $450,000 for fixed. Allocated fixed overhead totaled $430,000. The company tracks each item in an overhead control account before allocations are made to individual jobs. The fixed overhead spending variance for August was $15,000 unfavorable for fixed. Required: Make journal entries to record the actual costs incurred as well as the variances for August.
(3) MILKBOTTLE bought a 2,000-acre island for $10,000,000 and divided it into 200 equal size lots. As the lots are sold, they are cleared at an average cost of $5,000. Storm drains and driveways are installed at an average cost of $8,000 per site. Sales commissions are 10% of selling price. Administrative costs are $850,000 per year. The average selling price was $160,000 per lot during 2025 when 50 lots were sold. During 2026, the company bought another 2,000-acre island and developed it exactly the same way. Lot sales in 2026 totaled 300 with an average selling price of $160,000. All costs were the same as in 2025. Required: Determine operating income for both years using both absorption costing and variable costing.
(1) Compute the contribution margin ratio. (4%)
(2) Compute the unit price. (4%)
(3) Compute the margin of safety ratio and the degree of operating leverage. (8%)
(4) What is the relationship between profit ratio, contribution margin ratio and margin of safety ratio? (4%)
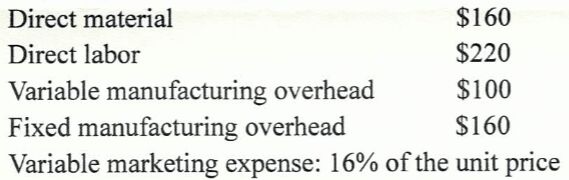
4. Taipei Company produces a special toy. The various unit costs are as follows: Suppose Taipei uses a 25% markup on the full unit cost. Compute the unit price of the toy. (10%)
(1) Compute the return on investment of Agnetha division. (10%)
(2) Compute the return on sales of Agnetha division. (10%)
 阿摩線上測驗
登入
阿摩線上測驗
登入
 Required: