3. During 2022, a construction company changed from the cost-recovery method to the percentage-of-completion method for accounting purposes but not for tax purposes. Gross profit figures under both methods for the past three years appear below: 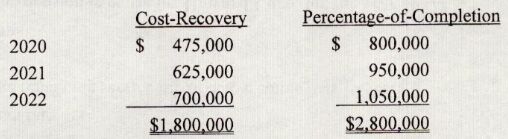
Assuming an income tax rate of 40% for all years, the effect of this accounting change on prior periods should be reported by a credit of what amount on the 2022 retained earnings statement?
 阿摩線上測驗
登入